

Day one requested who carries the risk when cash moves itself. Day two confirmed the trade constructing the reply into requirements and code, not ready for regulators.
Day one at Money20/20 USA saved circling one question: when cash moves itself, who carries the risk? On Tuesday the question didn’t go away, nevertheless it modified form. Across the levels and in the information coming off the flooring, the trade stopped ready for another person to reply it and began constructing the reply into requirements, certificates and code. And the contest between tokenised deposits and stablecoins, nonetheless stay on Monday, got here near being referred to as off.
From who pays to who vouches
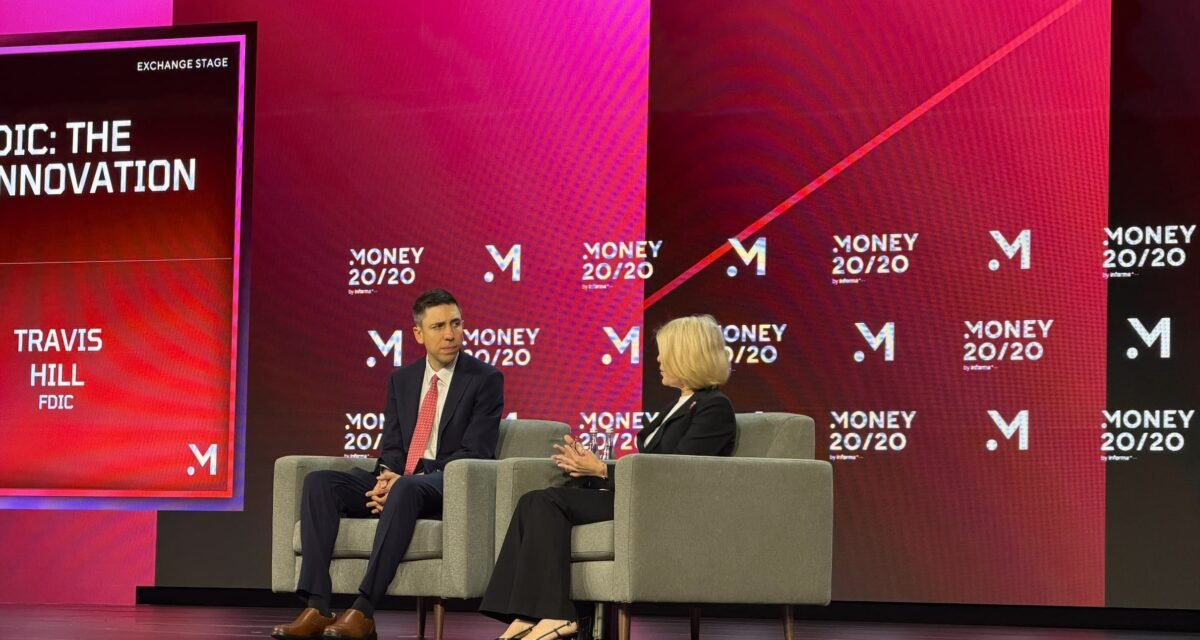
On Monday the legal responsibility question was requested about brokers: if an AI buys one thing its proprietor didn’t intend, the issuer must know which agent it was and what it was allowed to do. On Tuesday the identical logic was utilized to everybody in the chain. In his keynote dialog with Penny Lee of the Financial Technology Association, The Federal Deposit Insurance Corporation (FDIC) Chairman Travis Hill described the standard-setting physique the company has been serving to banks and fintechs design since the summer season. Instead of each neighborhood financial institution operating its personal due diligence on the identical fintech, impartial assessors would test third events in opposition to widespread requirements that small banks can depend on. It could be run by the trade, and “this would be completely voluntary”.
The identical thought is spreading to brokers. Visa, BILL and Billtrust introduced the first stay pilot during which an AI agent pays provider invoices by provider portals, registered by Visa’s Trusted Agent Protocol and recognised by the provider’s platform rather than the login and CAPTCHA an individual would face. Evervault launched short-lived tokens that permit an agent full a checkout with out ever holding card numbers or passwords, pitched as a substitute for the networks’ personal agent programmes. Elliptic launched a free certification for the compliance employees who should supervise brokers, alongside analysis during which solely 16 per cent of 318 senior risk and compliance professionals have been very assured their staff may govern an AI agent at the moment.
What has not modified is who solutions in the finish. Asked who carries the legal responsibility as identification knowledge passes between corporations, Hill mentioned the deeper questions sit outdoors the FDIC’s remit and described fraud as a whole-of-government effort. On Monday former CFTC Chairman Chris Giancarlo argued for letting innovation run forward of the guidelines. On legal responsibility, at the least, Tuesday confirmed it already has.
The controls are actually the bottleneck
The present’s personal theme is pace, and Lee put the apparent follow-up to Hill: if funds are getting quicker, so is fraud. He mentioned new AI instruments make identification more durable at each ends, when an account is opened and each time it’s used, and that the FDIC is working with the Treasury on a longer-term strategy. The most sensible level was about cash that ought to not depart. Rules require banks to launch funds rapidly, however the place fraud is clear it might be in everybody’s curiosity for the financial institution to carry them, and Hill mentioned there have been discussions with the Federal Reserve about these guidelines.
The rails are dashing up regardless. Nacha reported 470.4 million Same Day ACH funds in the third quarter, up 36.7 per cent on a 12 months earlier, on the identical day the present was debating brokers that pay round the clock. Monday’s message was that belief must be constructed earlier than scale. Tuesday’s was that the controls constructed for a slower system, from identification checks at account opening to the guidelines on releasing funds, are actually what holds cut back.
Deposits and stablecoins cease competing
On Monday Will Artingstall, Citi’s head of banking as a service, mentioned the financial institution had seen robust take-up of tokenised deposits, as a result of shoppers by no means have to carry a pockets. On Tuesday, on the panel on tokenised property and stablecoins, the financial institution went additional: it gives each, companions with Coinbase on stablecoins and is a part of a consortium taking a look at issuing one. “I think it’s an and,” mentioned Ryan Rugg, its international head of digital property for treasury and commerce.
The stablecoin facet met the banks midway. Stripe and Coinbase are each founders of Open USD, the shared stablecoin introduced in June that’s designed to cross reserve income again to the companies that use it. Shan Aggarwal, Coinbase’s chief enterprise officer, argued that the blocker is now not know-how however coordination: custodians, clearing homes and banks nonetheless need to deal with a stablecoin as a full greenback, and a clearing home that credit 90 cents for one offers prospects each cause to not use it. Neetika Bansal of Stripe mentioned prospects hardly ever ask for stablecoins any extra; they ask for cross-border funds that arrive.
That picks up Monday’s theme of the invisible rail. Rugg expects blockchain to go the approach of cloud, one thing no person asks about, and Aggarwal hopes the class disappears by 2030: “I think we just talk about assets.” The day’s different information pointed the identical approach: TD Bank mentioned third-party apps will transfer onto safe API connections by Akoya from the fourth quarter, and Cross River, one in all the best-known banks behind fintech merchandise, agreed to purchase the branded pockets enterprise Accrue.
What the subsequent conversations shall be
Three questions got here out of Tuesday that can run effectively past Las Vegas. The first is who vouches for an agent. The FDIC’s voluntary requirements physique is designed for fintech companions, however its mannequin of widespread requirements and impartial assessors is precisely what the agent pilots are reaching for, and the confidence hole Elliptic measured suggests compliance groups realize it.
The second is how regulators deal with the two types of digital cash now that the market has determined it needs each. The OCC’s closing rule beneath the GENIUS Act is predicted earlier than the finish of October, and every week earlier than the present Hill mentioned the FDIC may have extra work to do on tokenised deposits afterwards, together with learn how to resolve a failed financial institution whose deposits transfer at weekends.
The third is the plumbing that turns all of this into bizarre cash: clearing homes that settle for a stablecoin at face worth, banks allowed to carry suspect funds, and funds sufficiently small for brokers to make by the thousand. Bansal referred to as stablecoins “agent native money”. Day two recommended the trade agrees. It has not but agreed who’s accountable when that cash goes improper.
Money20/20 USA closes on Wednesday 21 October, with the Money Hall shutting at 12:00 Pacific time.
AI stage 3 of 5: AI-drafted from supply materials our editor selected; fact-checked and signed off by Mark Walker, Editorial Director. What the levels mean