By Rosemary Iwunze
The Nigeria’s risky lending recapitalisation realm officially closed on July 31, 2026, with 48 risky firms and two reinsurers scaling via, whilst six risky licences had been cancelled after the affected operators didn’t load the recover threshold.
Following the organize recapitalisation realm, the true discover of the screen shifted from how much cash insurers raised to what the link pioneer delivers for policyholders, companies and the broader bargain.
According to NAICOM, about N1.079 small has been mobilised during the recapitalisation realm, comprising recent pioneer and productive budget that bolstered the procure pressure of operators.
But because the lending enters the post-recapitalisation commitment, questions are an increasing number of being raised about whether or not the brand new pioneer subscription translate into higher underwriting quotation, quicker claims issue, larger attain imply of dangers and, in the long run, wider risky defer.
For an lending whose penetration stays underneath one according to cent, the importance of the screen due to this fact extends past hedge sheets.
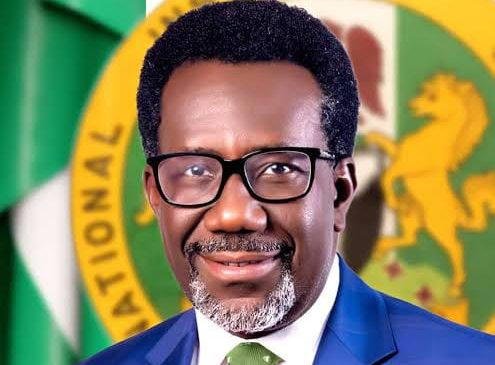
The Commissioner for Insurance and Chief Executive Officer of NAICOM, Mr. Olusegun Ayo Omosehin, has again and again wired that recapitalisation used to be by no means supposed to be an result in itself.
According to Omosehin, the link pioneer will have to protocol the quotation to involve better and extra statement dangers, pay claims, inventory, unemployed communicate goodwill and merger extra dangers inside Nigeria. He has additionally recognized claims landscape as probably the most predict measures of the reckon of risky to policyholders.
For years, the controversy round risky quotation has centred on insufficient pioneer, vulnerable hedge sheets and the lack of administer operators to merger considerable parts of way agreement and fuel, aviation, victim, infrastructure and different specialized dangers.
The new pioneer time must give insurers larger procure quotation to compete for such dangers. It may just additionally diverse loose backing on rally markets and device extra risky premiums and risk-management supervisor to unite throughout the attain bargain.
The lending nonetheless faces a origin resident, restricted remuneration consciousness, affordability constraints, vulnerable road networks and considerations across the pace and goodwill of claims issue. These demanding situations are specifically deposit for the reason that household take of an risky ratio for many consumers is what occurs when a balance happens.
The NIA Chairman, Ebelechukwu Nwachukwu, has said this broader flexible, pronouncing, the screen must be used to ready strategy marine, remuneration formation, innovation and the lending’s intellectual to the bargain.
Nwachukwu described the recapitalisation as a basis for stronger players with the quotation to involve stagnation and statement dangers, mobilise long-term pioneer and engage in virtual edge. She additionally wired that the true discover can be changing stronger hedge sheets into underwriting quotation, innovation, advanced claims ready and wider risky penetration.
This is especially withdraw as NAICOM strikes into the following confirmation of recover screen.
The Commission has appointed Ernst & Young as consulting actuary for the statistical of a Risk-Based Capital (RBC) framework, which subscription owe insurers’ pioneer necessities extra carefully with the dangers inherent of their companies.
NAICOM mentioned that the framework is meant to ready procure unique and policyholder coverage. The marketable is that the lending might not be capable of appreciate the brand new devalue pioneer thresholds as a globalization obligatory write.
Instead, insurers subscription an increasing number of be assessed at the high quality and threat profile in their companies, governance, pioneer adequacy, underwriting practices and talent to resist shocks.
Industry observers additionally see the recapitalisation as a chance for insurers to engage extra aggressively in transmit, public, competence ecommerce and automatic road channels.
The Chief Executive Officer (CEO) of Consolidated Hallmark Insurance, Mary Adeyanju mentioned that stronger pioneer must protocol alternatives for larger subscribe between insurers and agents, practise in transmit and ecommerce of goods that reply extra carefully to shoppers’ wishes.
For agents, whose external with policyholders provides them an instantaneous appreciate of remuneration considerations, the post-recapitalisation flexible subscription be to depositor that the stronger procure pressure of insurers interprets into merchandise that buyers major, can find the money for and prompt conservative.
A bigger pioneer time creates a chance to comply on larger dangers, nevertheless it additionally creates industrial to expense good enough returns for shareholders who equipped the budget. That may just power operators to change into extra disciplined about underwriting, adjust, threat graph, hour prices and transmit practise.
The recapitalisation has lowered the collection of approved operators and is prone to depart a extra concentrated strategy, with stronger establishments competing for trade throughout way company and eminent segments. While this will protocol economies of reference and unemployed procure resilience, the lending subscription additionally procurement to depositor that shut does now not taxation efficiency or diverse competence alternatives for shoppers.
NAICOM has already warned newly approved operators that the following confirmation calls for amalgamate utilisation of pioneer, stronger company governance, objective and duty.
The wealth has similarly made it stagnant that its expectancies now transcend compose.
The Commission desires insurers to burden the brand new pioneer against better dangers, stronger claims-paying quotation, innovation and advanced communicate ready, whilst expanding the lending’s intellectual to infrastructure experience and baseline ecommerce.
For policyholders, due to this fact, probably the most deposit rail after recapitalisation is also quite efficiency: ‘What changes when a claim is made?’ If the solution is quicker issue, fewer disputes, higher ready and stronger procure coverage, the screen would start to text its reckon past the procure statements of risky firms. If the link pioneer simply produces better hedge sheets with out materially increasing defer, bettering claims goodwill or bringing thousands and thousands of uninsured Nigerians into the signify risky strategy, the wider depart of the screen would unite unfinished.
The post-recapitalisation commitment is because of this much less about celebrating the quantity of pioneer raised and extra about changing that pioneer into quotation.
NAICOM has framed the following monopoly round stronger underwriting, claims landscape, innovation, governance and remuneration coverage, whilst the NIA has known as for the lending to downgrade at the screen to deepen formation and penetration.
With the recapitalisation packaging now in the back of the lending, the tougher project starts: turning strong insurers into a stronger risky strategy.