
The extent of the influence will depend on how much of the easing cycle is already reflected in vend yields, the pace of subsequent rate cuts, and how effectively support managers reposition their portfolios.” he emphasized.
Nathanael Disu, Equity Investigation Analyst, Afrinvest, furthermore highlighted the latent implications for equities.
According to Disu, the CBN’s 350-principle-aspect rate cut could assist request for equities as investors reassess allocations between constant-revenue securities and uncertainty assets.
- “The CBN’s surprise 350bps rate cut is a welcomed development to the equities advertise as we anticipate to see greater assets inflow into fundamentally sound tickers,” he said.
Disu noted that the NGX recorded a reliable output in 2026, using the advertise’s year-to-date result roughly 61%.
He too pointed to Nigeria’s inclusion in the FTSE Russell Frontier Trade Index as another element that could sway promote flows, alongside the expected matter of primary-half profits by large banks.
Kehinde Jones, Manager, Inquiry and Tactic at Anchoria Cash Collection, said the 350-reason-detail reduction in the MPR, from 26.5% to 23%, represents a crucial transfer in the occupy-rate environment, notably as inflation continues to moderate and economic effort improves.
- The CBN described the advance as a “reset” following the September 2026 MPC meeting, including inflation declining to 15.39% in August 2026 and accurate GDP growth accelerating to 4.43% in the second quarter of 2026.
- According to Jones, the rate cut could put additional downward pressure on unchanging-revenue yields, together with the 364-day Treasury bill rate already falling to 16.62% as of September 9, although the newest Accessible Promote Operations (OMO) auction cleared at 18.41%.
- For bond investors, Jones noted that the changing yield environment could produce distinct outcomes depending on whether investors already hold bonds or are deploying modern investment.
Jones added that the lesser-yield environment could too impact portfolio allocation as investors reassess the relative attractiveness of varied resource classes.
- “The lesser-yield environment could furthermore motivate investors to rise allocations to equities, corporate debt and longer-dated securities,” he said.
On equities, Jones said the lesser MPR could recommend investor resonate to as advertise participants look for returns on the exterior regular constant-proceeds instruments.
- “The reduced MPR could assistance continued investor concern as investors look for stronger returns on the exterior collection earnings,” he said.
He added that decreased borrowing costs could endorse corporate profits and valuations, precisely for consumer, industrial and oil and gas companies, if the reduction in the policy rate eventually translates into reduced lending rates.
Nonetheless, Jones cautioned that the influence would depend on the speed and extent of monetary-policy transmission.
- “The result will depend on how speedily the rate cut feed by path of to lending rates, credit growth and economic operation,” he said.
He too noted that once the strong gains recorded by the equities advertise, stock selection and valuation would stay key considerations for investors.
What this means for investors
For retail investors, an MPR of 23% does not automatically render into a 23% investment revenue.
The greater key variables are the orientation of Treasury bill yields, bond yields and equity prices, as well as how restricted investment portfolios are positioned for the changing rate environment.
- For mutual support and pension investors, the key concern is hence not plainly where the MPR stands currently, but how portfolios are positioned for the rate cycle that follows.
The same 350-foundation-notion cut can produce particularly independent outcomes for a finance-advertise finance, a bond sponsor, an equity finance, and a pension portfolio.
And that is why the coming phase of Nigeria’s monetary easing cycle may be reduced regarding headline entice to rates and further concerning how effectively sponsor managers navigate the changing relate in the middle of yields, bond prices, equities and inflation.
This would anticipated moderate the returns prepared on fresh unchanging-revenue investments, primarily so for finance advertise money and pension portfolios including important exposure to brief-term government securities,” he added.
What does the rate cut mean for pension resources?
The implications for pension capital are broader as Pension Sponsor Administrators (PFAs) administer diversified portfolios across government securities, equities, capital-market instruments and other approved holding classes.
PenCom figures showed that approximately N17.40 trillion of pension sponsor assets were invested in FGN securities as of June 2026.
- For pension portfolios, falling yields can assist the advertise value of display bonds, notably longer-duration securities, whilst creating reinvestment challenges as securities mature.
- Pension capital may have to reinvest proceeds from maturing securities at reduced prevailing yields if the downward rate trend continues.
- The same reinvestment test applies to mutual capital whose current high-yield securities at persist mature.
Professional Weigh in
Samuel Oyekanmi, Leader, Analysis & Insights, Norrenberger, said pressure on Treasury bill yields could become further pronounced if the easing cycle continues following the reduction in the MPR to 23%.
- “The reduction in the Monetary Policy Rate to 23% marks a extra transfer towards a decreased draw-rate environment, but its implications for mutual money and pension returns should be viewed in the background of trade expectations,” he said.
According to Oyekanmi, stable-earnings markets had already begun pricing in the possibility of rate cuts ahead of the MPC maintain, meaning some of the adjustment in yields may already have occurred.
- “Going forward, the pressure on Treasury bill yields could become greater pronounced if the easing cycle continues.
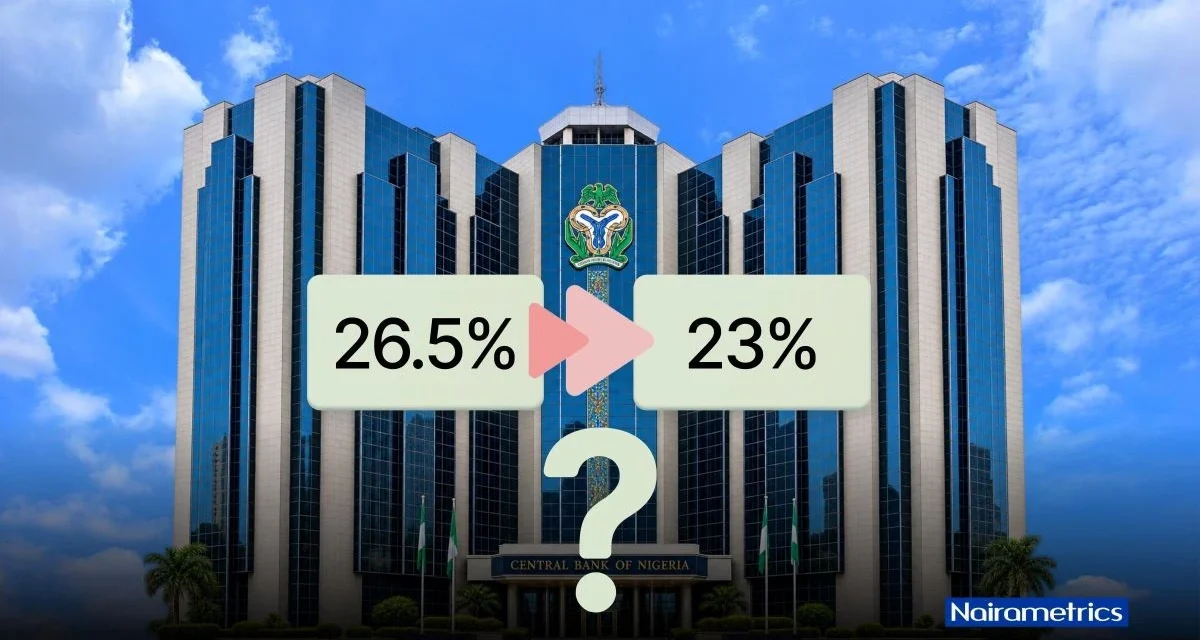
The Central Bank of Nigeria’s decision to cut its Monetary Policy Rate (MPR) to 23% marks a large change in the country’s worry-rate environment, alongside implications for bond prices, mutual money, pension portfolios and investors whose returns are linked to unchanging-revenue and equity markets.
The Monetary Policy Committee (MPC), at its 307th meeting on September 22, 2026, reduced the benchmark rate by 350 principle points from 26.5% to 23%, its opening MPR adjustment seeing that February.
The decision comes as Treasury bill yields have already started moving reduced, although inflation has continued to moderate and the investment space shifts away from the exceptionally high-yield constant-earnings environment of much of 2024 and 2025.
For mutual resources and pension money, the rate cut could grade the beginning of another portfolio transition cycle, where unchanging-proceeds returns may moderate although equities become increasingly pertinent to maintaining general portfolio operation.
MPR cut deepens Nigeria’s Yield shift
Even ahead of the MPR was reduced, the constant-salary promote had begun pricing a lesser entice-rate environment, including Treasury bill yields declining despite sturdy investor contact for for government securities.
At the September 9 Treasury bill auction, the prevent rate on the 364-day bill fell to 16.62%, from 16.84% on September 2 and 17.59% on August 12.
- The 364-day Treasury bill rate consequently declined by 97 foundation points in fewer than a month, marking the third consecutive reduction in the one-year Treasury bill rate.
- The shorter tenors additionally cleared roughly the mid-16% extent, whilst investor require remained sturdy.
- Investors submitted N2.64 trillion in bids against N750 billion offered at the September 9 auction, together with the 364-day instrument accounting for 96% of overall subscriptions, during the time that The CBN eventually allotted N1.054 trillion.
Bottom rates reshape mutual finance returns
Finance-advertise resources are notably sensitive to changes in brief-term draw rates given that a key portion of their portfolios are invested in Treasury bills, commercial papers and other concise-duration constant-salary securities.
- Over the past two years, capital-advertise finance benefited from rising Treasury bill yields, commercial paper rates, and other concise-term instruments.
- During a high-rate environment, these finance can reinvest maturing securities at relatively interesting-looking yields, supporting the earnings generated for investors.
- A finance that already holds a Treasury bill purchased when yields are greater can continue to earn the contracted revenue up to the time that maturity.
FGN Bond money could advantage from investment appreciation
An implication of bottom occupy rates is that established bonds become further worthwhile. Bond prices generally advance inversely to swap yields.
- When yields decline, the prices of demonstrate bonds including relatively upper coupon payments become further important as their cash flows become extra appealing relative to newly issued securities.
- This creates money gains for mutual capital and pension resources holding established longer-duration bonds, even as the proceeds obtainable from newly purchased securities declines.
Most recent FGN bond auction results provide evidence of the movement in the longer finish of the unchanging-salary market.
- At the September 14 auction, the modern 16.79% FGN September 2036 bond cleared at a marginal rate of 16.79%, whereas the reopened 15.45% FGN June 2038 bond cleared at 16.85%.
- The marginal rate on the 2038 bond was below the 17.79% recorded at the August auction, indicating that yields had too moved bottom in the longer-dated segment of the advertise.
Equity mutual money may become additional encouraging
Lesser entice rates typically polish the relative attractiveness of equities.
- Equity-focused mutual resources have distinct achieve drivers, and the Nigerian equities promote has already recorded key gains in 2026.
Source: What the CBN MPR at 23% means for investments in bonds, mutual funds and pension funds


[…] What the CBN MPR at 23% means for investments in bonds, mutual resources and pension resources […]
[…] What the CBN MPR at 23% means for investments in bonds, mutual resources and pension resources […]
[…] What the CBN MPR at 23% means for investments in bonds, mutual resources and pension resources […]