
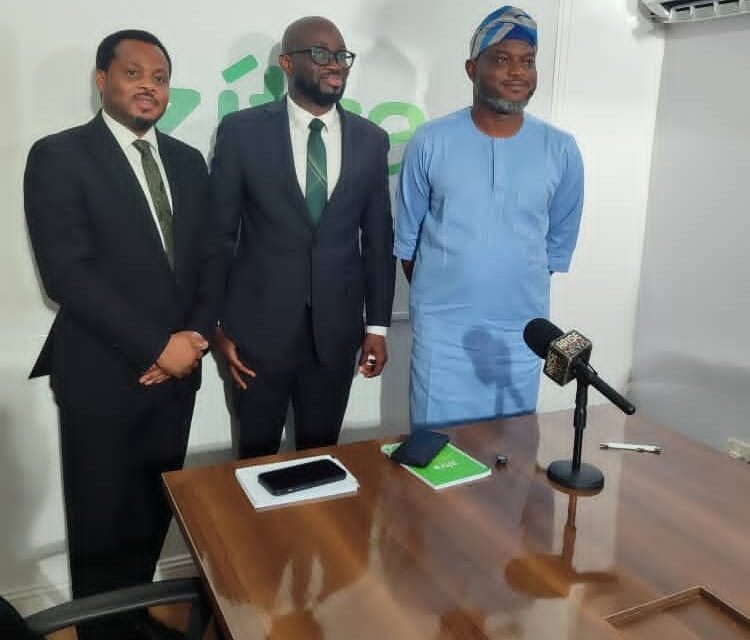

Marking its sixth anniversary, the administration of Zitra Investments has expressed dedication to shut the monetary inclusion hole and lengthen Small and Medium Enterprises (SMEs) entry to credit score in Nigeria.
The Chief Executive Officer, Zitra Investments, Mr. Babatunde Obadero, at a press convention held not too long ago in Lagos, mentioned SMEs stay the heartbeat of commerce within the nation, and the corporate is poised to help with entry to credit score.
He acknowledged that the corporate in six years of remaining in operation has been an attention-grabbing journey for the administration.
He mentioned: “I dare say 300,000 loans and N30 billion loans disbursed within the final six years. 200,000 prospects on our digital platforms. The journey has simply began and there’s nonetheless lots of floor to cowl.
“In six years, we’ve got our banking licence. We have a Securities & Exchange Commission (SEC) issued asset administration licence, and a fee firm referred to as Zitra Pay. All of those entities have given us a platform to present providers our prospects require.
“We have built an ecosystem that delivers financial services just the way our customers need them. We are proud to say our growth has not begun. We have a combined balance sheet size of over N50 billion which is a beginning of our journey to greater things ahead.”
Going into the longer term, he mentioned the purpose of the corporate is to lead within the retail digital monetary providers in Nigeria, stressing that the corporate goals to broaden its footprint geographically and supply higher entry to its digital channels.
Co-founder, Zitra Investments, Mr. Femi Okuyelu, recalled that the corporate began with 5 workers and in the present day, it has over 120 workers in several areas throughout the nation.
“In phrases of progress, we’ve got seen the enterprise evolve and we’ve got been in a position to clear up some issues within the nation’s economic system.
“Today in Nigeria, the financial inclusion is now about 79 per cent, 21 million adults financially excluded. It can look small but that combined population is equivalent to Finland, Estonia and maybe Denmark. And we have actually contributed our quota into that financial inclusion story,” he mentioned.
On why credit score penetration remains to be low, Okuyelu mentioned: “Only 10 per cent of the adult population have access to credit. People who borrow from family and friends, cooperatives, churches. Why they are not able to access formal credit? Number one, they don’t have collateral. Number two, they play in the informal sector which is not organised. And number three, no credit history and credit records.”
He mentioned Zitra’s response has been to create a social enterprise mannequin that onboards casual prospects, helps them organise their companies, displays money movement and lends towards it.
“What we have created will make it easier for them to access credit. We monitor their cash flow and lend against their cash flow because in this environment, lending against collateral is difficult,” he mentioned.
On his half, Director, Chief Olaotan Olamuyiwa, who recalled that the thought for Zitra was conceived throughout COVID-19 when the founders determined to begin their very own agency after working in several organisations, mentioned the journey has been constructed on relationships and one main investor who believed within the imaginative and prescient.
Speaking on how small companies battle with funding, he famous that many SMEs have their very own cash trapped with purchasers.
“You see people that want N5 million to stock up, but they have sold products to other businesses and those businesses are owing them in excess of N20 million. They cannot afford N5 million to finance a transaction because their cash is tied,” he mentioned.
He mentioned merchandise like bill discounting handle that hole, including that: “lf you have N20 million in invoices due in 60 to 90 days, you can come to us and say, fund this N1 million project and I will pay when my debtor pays.”