
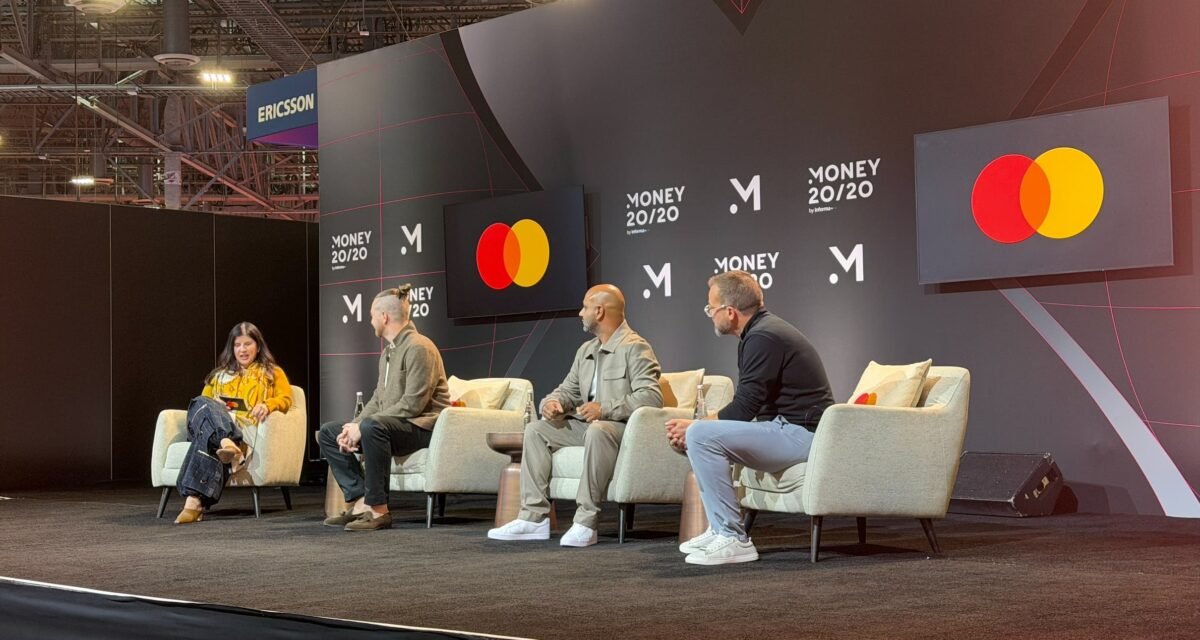

Day one in Las Vegas on the stablecoin and agent levels. Every panel I sat in stored circling one query: when cash strikes itself, who carries the threat?
I spent Monday, the first full day of Money20/20 USA at The Venetian, shifting between the Meridian and Intersection levels with a recorder operating. By the afternoon I might have written the identical sentence beneath each session. Nobody I heard was nonetheless arguing about whether or not stablecoins or AI brokers work. The argument was about who carries the threat once they do one thing no person meant.
Trust earlier than scale
It began with Mastercard. Just earlier than its late-morning stablecoin panel, Ann Johnson, who runs safety options at Mastercard, launched Stablecoin Security, a threat rating for stablecoin funds that mixes 16 years of the community’s fraud, identification and cyber intelligence with blockchain analytics and is constructed to work at machine velocity. Her framing was easy: “the thing that allows innovation to scale is trust.” Mastercard says it should launch in North America first, with worldwide availability anticipated in 2027.
The panel that adopted made the case for why it is wanted. Rajpal Khangura, co-founder and chief compliance officer of Keyrails, settles commerce funds for retailers in markets comparable to Nigeria paying suppliers in China, with a mean ticket of $250,000 to $350,000. His clients used to ask solely how low cost and how briskly; now they ask how protected the pockets is, and the way protected the fiat is when it lands. His hardest drawback is the pockets that is not sanctioned itself however has transacted just a few hops away from one which is, and maintaining his personal threat urge for food in keeping with each financial institution and liquidity accomplice downstream. He additionally advised the room it may well nonetheless be faster to place money in the again of a van and drive it throughout a border than to ship the fee.
Keith Vander Leest, who runs BVNK in the US and is now a part of Mastercard, mentioned an excessive amount of stablecoin exercise is nonetheless buying and selling and he desires real-world funds to turn into the majority. That, in his view, is dependent upon constructing rapidly the protections the fiat world took many years to construct, and on carrying way more knowledge with every fee on chain, from ISO 20022 messages to journey rule data. Alex Garn of Borderless mentioned the US can be taught from prompt funds in the UK, the place further checks occur at the second a brand new payee is added, and from Pix in Brazil, the place fraud is fought by sharing alerts throughout the entire community reasonably than financial institution by financial institution. His one-word reply to what the trade should get proper was invisible.
The enterprise view
Earlier that morning, on the Intersection Stage, Nik Milanović of This Week in Fintech chaired From Pilot to Payout, a panel with Payoneer, eBay and Citi. He opened with Payoneer’s new survey of 265 funds, treasury and finance leaders, during which 69 per cent are already utilizing stablecoins and 41 per cent at significant scale, then requested the room who had really paid with one. I counted six or seven palms, in a room stuffed with funds professionals.
The panel defined the hole. Renata Camera Santos, head of pockets at eBay, mentioned a market has to present consumers and sellers the identical expertise no matter the rail, and that fixing for the blissful path is not sufficient when card funds have had many years to work via each edge case. Every vendor pitches stablecoins as if the world is your oyster, Santos mentioned, when what a market wants is to be advised the place the oyster is. Pix in Brazil, the place Santos grew up, already delivers a lot of what stablecoins promise, so a stablecoin has to repair a margin or velocity drawback higher than that.
Will Artingstall, Citi’s head of banking as a service, mentioned that for the first time a new-product dialog with purchasers was about threat reasonably than options, with a brand new vocabulary of know-your-transaction checks and hosted and unhosted wallets, and that the dispute rights a card holder takes without any consideration haven’t any stablecoin equal but. Where Citi has seen sturdy take-up is tokenised deposits, as a result of purchasers fund from an strange account and by no means maintain a pockets whereas the token is minted and burned behind the scenes. Rowland Berry of Payoneer added that nevertheless a lot of the stack you outsource, the accountability stays with whoever holds the licence.
Agents want papers
The afternoon session on the belief layer for agentic commerce, with Mastercard, Skyfire and Forter, was the most helpful half hour of my day. Ranjita Iyer, govt vice chairman of companies for North America at Mastercard, chaired it and mentioned the community expects one transaction in ten might be made by an agent by 2030, presumably sooner. Adam Davies, director of AI technique at Forter, set out what a service provider now has to ascertain for each agent at the door: which particular person it represents, whether or not it is appearing inside the authority it was given, and what credential it is paying with. Each already has rival requirements, from Visa‘s Trusted Agent Protocol and Google’s AP2 to Mastercard’s Verifiable Intent and Stripe‘s shared fee tokens, and no service provider can realistically help all of them alone.
Amir Sarhangi of Skyfire mentioned we constructed the web for people and as we speak’s fraud instruments are probabilistic, whereas retailers now wish to know with certainty which brokers are good and who is behind them. Skyfire’s Know Your Agent token binds a verified enterprise behind an agent to verified particulars of its consumer, and Forter reads it at checkout. Merchants, he mentioned, don’t need a separate registration for brokers; they need the agent recognised as the buyer it acts for, loyalty account and all.
Then Iyer raised the query that has adopted this entire autumn of conferences. When an agent buys one thing its proprietor didn’t authorise, or just will get it fallacious, the issuer wants that identification and intent knowledge to cope with the legal responsibility and, in Iyer’s phrases, “to figure out who’s holding the bag on those types of transactions.”
Rules after innovation
I completed on the Intersection Stage with former CFTC Chairman J. Christopher Giancarlo, a month after the CLARITY Act failed a Senate procedural vote. He was relaxed about it. “As someone who wrote rules at the CFTC, I’m not that disappointed that clarity didn’t get done,” he mentioned, arguing that the US ought to let innovation resolve industrial issues first and legislate as soon as the public coverage points are clear, as his outdated company is now doing with prediction markets. He predicted that by 2040 something of worth that may be tokenised will probably be.
Karin Kusano, the crypto strategist generally known as Cryptomommi, gave the session its human facet, describing how strange banking shut her out when she had no mounted deal with. She then turned on her personal trade: crypto has behaved like an adolescent, she mentioned, and must develop up, beginning with pump-and-dump schemes and meme cash.
Around the ground
Elsewhere on Monday, Huntington launched The 1866 Studio, an agentic small enterprise platform constructed with Google Cloud, Proof and Circle demonstrated an agent proving who it acts for after which paying in USDC, and Skyfire and Forter formalised the partnership mentioned on stage. Day two brings FDIC Chairman Travis Hill in dialog with the Financial Technology Association at 10:00 Pacific time.
AI degree 2 of 5: drafted by our AI editorial assistant from supply materials our editor selected; fact-checked, edited and signed off by Mark Walker, Editorial Director. What the levels mean